
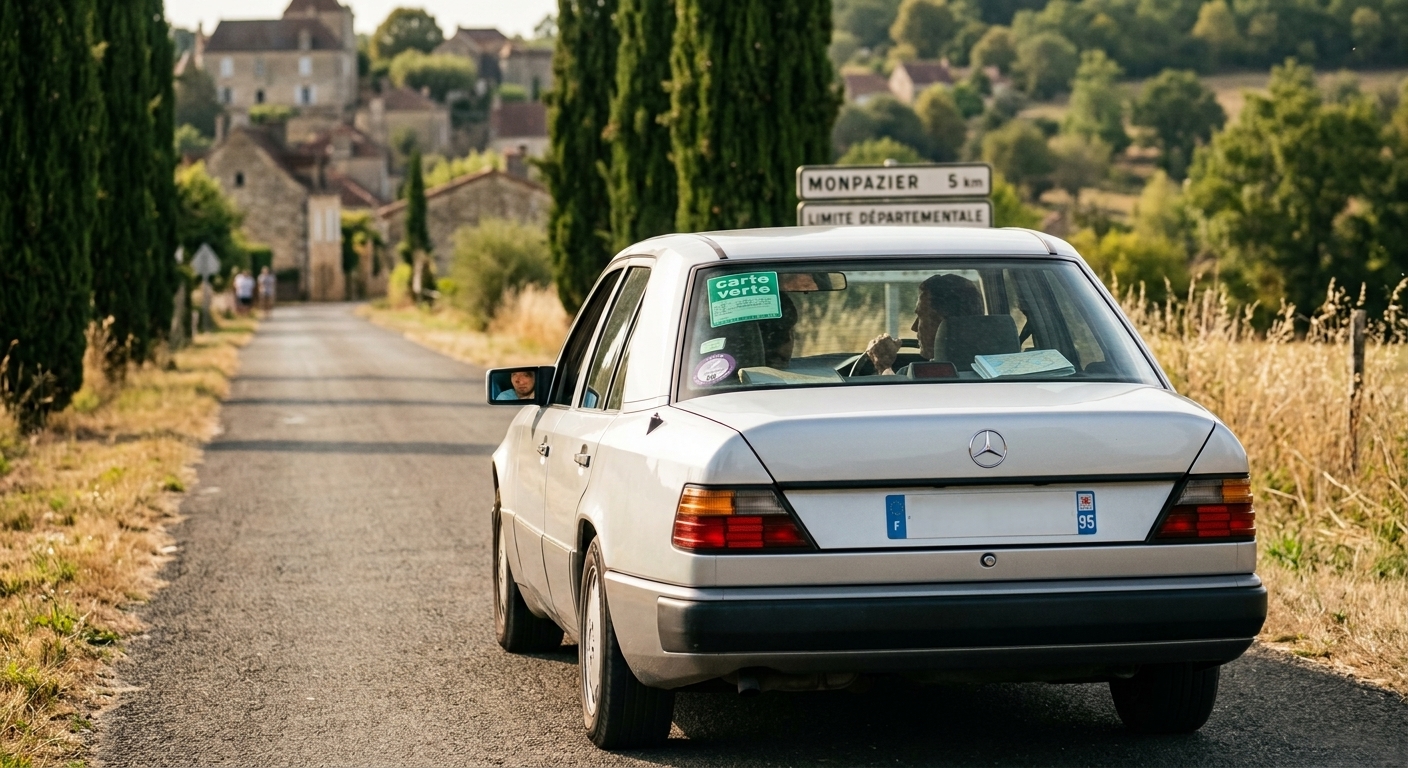
You brought your own car when you moved. It runs perfectly and you know its history. Yet a French insurer cannot issue a final policy until the paperwork advances. Sequence matters here more than price, and getting it wrong leaves a car you cannot legally drive.
Insurance and registration are linked
Start with the principle that governs everything else. The two processes feed each other.
A French insurer normally needs your registration details to issue a definitive policy. Those details come from the French registration document, the carte grise.
Registration, meanwhile, requires a compliant vehicle and a complete file. It does not happen in an afternoon.
Between the two sits a gap of several weeks. That gap is where most newcomers get stuck.
Guides on insuring an imported car France rarely explain this overlap. It is, however, the whole problem.
Treat insuring an imported car France as a project with stages. Each stage unlocks the next, and skipping one blocks everything behind it.
Cover during the procedure
Here is the question every importer asks first. It has a practical answer.
Temporary arrangements usually exist while registration is pending. Insurers are familiar with this situation.
Contact an insurer before the car arrives, not afterwards. Explain the timeline and ask what they can issue immediately.
Driving uninsured is a criminal offence in France. No administrative delay excuses it, so never rely on a foreign policy without checking its territorial scope.
Ask your previous insurer in writing how long their cover extends. Verbal reassurance is worth nothing in a claim.
Keep every confirmation in writing. A provisional note protects you if a roadside check happens mid-procedure.
The homologation documents
This is where files stall most often. Gather these early.
The European certificate of conformity, or COC, proves the vehicle meets type-approval requirements. You request it from the manufacturer, not from an administration.
Allow real time for that request. Some manufacturers take weeks to issue it.
Certain older or unusual vehicles have no COC available. An individual approval procedure then replaces it, which takes longer and costs more.
Check this point before shipping anything. A vehicle without a route to approval is a very expensive mistake.
EU origin versus outside the EU
Two distinct administrative paths exist. Identify yours immediately.
A vehicle arriving from another EU country needs a tax clearance document, the quitus fiscal. No customs duty applies here. French VAT is normally due only if the vehicle counts as new in the fiscal sense.
A vehicle arriving from outside the EU must clear customs on arrival. Customs issue their own certificate, which replaces the quitus fiscal in your file.
Duty and French VAT then apply on that import. Rates and bases depend on the vehicle, so confirm them with customs directly.
An exemption exists for a genuine transfer of residence. Conditions are cumulative and strict. They typically involve a minimum period spent outside the EU, a minimum ownership period, and a resale ban.
Note one trap carefully. That customs relief does not automatically exempt you from every French tax on first registration.
The British case since Brexit
This situation deserves its own paragraph. Many owners still assume the old rules apply.
The United Kingdom now sits outside the EU customs union. A car brought from Britain therefore follows the non-EU path, with full customs formalities.
Plan for that step rather than discovering it at the port. Documentation gaps cause storage costs and delays.
Right-hand drive vehicles remain perfectly insurable in France. Some insurers price them differently, and a specialist broker helps here.
Headlight adjustment is usually required for a right-hand drive car. Treat it as part of the registration budget.
Roadworthiness testing
The contrôle technique often surprises importers. Rules vary with the vehicle’s situation.
A car beyond a certain age generally needs a recent test before registration. Recent means a matter of months, not years.
A test carried out in another EU country may be accepted for a vehicle already registered there. A test from outside the EU normally has to be redone in France.
Budget time for a possible retest. Minor non-conformities surface more often on imported vehicles.
Confirm the current requirement for your case before booking. These rules evolve, so rely on an official source.
The tax that catches people out
Now the financial trap of any import. It deserves your full attention.
France applies a CO2-based penalty on first registration, known as the malus. A used imported car has never been subject to it, so its registration in France counts as that first event.
The calculation does not use today’s scale. It uses the scale of the year the vehicle was first registered abroad.
An age-based reduction then applies, by brackets of months rather than pro rata. The reduction grows with the vehicle’s age until it reaches full relief.
In practice, a vehicle of roughly fifteen years or more escapes this penalty entirely. A recent, powerful import can conversely face a substantial bill.
A weight-based penalty follows comparable logic, and concerns more recent vehicles. Use the official simulator for any figure, since the result depends on emissions, power and the exact first registration date.
Run that simulation before you commit to shipping. Insuring an imported car France side is rarely the expensive part, this tax often is.
What the insurer needs afterwards
Once registration completes, the insurance file closes quickly. Prepare these items.
- The French registration document, or the provisional certificate issued first. :
- Your valid driving licence, exchanged if your situation requires it. :
- A written statement of your claims history from your previous insurer. :
- Proof of address and a French bank account for the direct debit. :
- Purchase and import documents, which insurers may request for an unusual vehicle. :
That claims statement matters more than people expect. It is the single biggest lever on your premium.
Insuring an imported car France becomes straightforward at this stage. The difficulty lies upstream, in the registration file.
Imported classic vehicles
Older imports follow a partly different logic. The distinction is worth knowing.
Vehicles above a certain age can qualify for a specific registration category. That status brings its own rules on use and testing.
Dedicated insurance schemes exist for such vehicles. They often combine limited mileage with agreed-value cover.
Discuss the intended use honestly with your adviser. Occasional leisure use and daily commuting are not the same risk.
The sequence errors that immobilise a car
Most import problems come from order, not from rules. Avoid these four.
First error: shipping before checking that a COC is obtainable. The vehicle then sits unregistrable.
Second error: assuming a foreign policy covers you indefinitely. Territorial and duration limits apply.
Third error: discovering the CO2 penalty after purchase. It can exceed the saving that motivated the import.
Fourth error: starting the insurance conversation last. An adviser consulted early reshapes the whole timeline.
A workable order of operations
Check that homologation is possible, then estimate the registration taxes. Confirm your customs path according to origin.
Arrange provisional cover before the vehicle moves, and keep written confirmation. Complete customs or tax clearance on arrival, then the roadworthiness test.
File the registration application, then convert your cover into a definitive policy. For insuring an imported car France, work with a bilingual adviser who can read both files.
This order looks longer written down than lived. Followed properly, it turns a stressful import into an administrative formality.

0 commentaires